


Volatility has created several opportunities across the fixed-income market in 2026. Persistent inflation, rising Treasury yields, changing Federal Reserve policy, and concerns about government borrowing have pushed bond prices lower, creating more attractive yields for investors willing to look beyond the recent market turbulence.
However, one of the biggest opportunities may be hiding in municipal bonds.
Traditionally favored by income-oriented investors seeking tax-exempt income, municipal bonds have experienced an unusually sharp repricing. A combination of elevated issuance, interest-rate volatility, and seasonal selling pressure has pushed yields to levels rarely seen since the global financial crisis. For investors, elevated yields, relatively strong credit fundamentals, and potential price appreciation could make municipal bonds one of the most compelling opportunities in fixed-income.
A Big Sell-Off
Traditionally, the municipal bond sector is fairly boring—a place where high-net-worth individuals and institutional investors tend to buy and hold. However, that doesn’t mean the fixed-income segment can’t experience bouts of volatility.
Right now, that appears to be the case, with the municipal bond market experiencing a dramatic reversal in September. Rising interest rates and unfavorable supply-and-demand conditions triggered widespread selling.
The Federal Reserve’s September rate increase, its first in three years, contributed to a broader Treasury market sell-off. Strong economic data, elevated energy prices, and persistent inflation concerns reinforced expectations that interest rates could remain higher for longer. By the end of September, the 10-year Treasury yield had reached approximately 5.30%, its highest level since 2007.
Municipal bonds experienced an even more pronounced repricing. The Bloomberg Municipal Bond Index declined 4.36% during September, contributing to a third-quarter loss of approximately 6.8%—its worst quarterly performance since 1981.
Several technical factors helped amplify the downturn in the muni sector.
Municipal issuance has remained unusually heavy. With inflation rising and expectations growing for higher interest rates, many states, cities, and other municipal entities issued large volumes of new bonds to take advantage of still-low interest rates. Approximately $600 billion in new bonds entered the marketplace during 2026, and if that pace continues, the year could set an annual record.
At the same time, seasonal reinvestment demand weakened, reducing the capital available to absorb new securities. Buyers stepped back from munis as other fixed-income opportunities—such as CLOs and private credit—competed for attention. As bond prices declined, investors increasingly sold existing holdings to realize tax losses, adding further pressure to an already struggling market.
The result was more bonds and more sellers, which pushed municipal securities prices lower.
A Rare Buying Opportunity
For investors willing to tolerate near-term volatility, the sell-off has created a valuable entry point.
Take yields, for example.
Interest payments from most municipal bonds are exempt from federal income taxes, and depending on the investor’s state of residence and the bond’s issuer, that income may also qualify for state and local tax exemptions. This makes the yield comparison with taxable bonds particularly important. The taxable-equivalent yield (TEY) shows what investors would need to earn on a taxable bond to match the after-tax income of a muni.
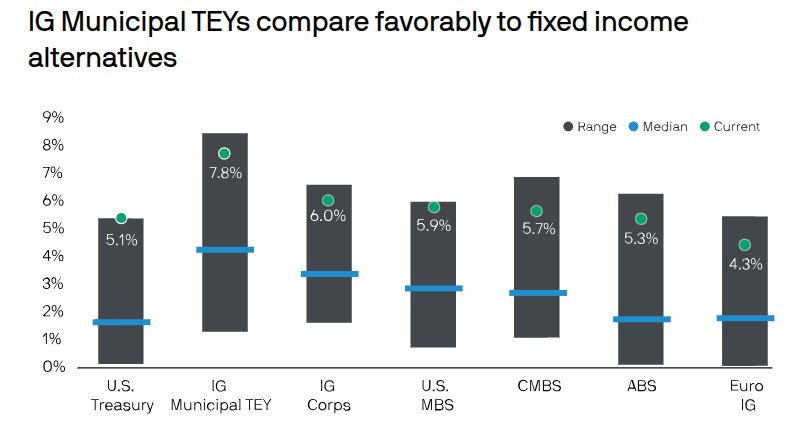
Right now, the TEY for municipal bonds is 8% for investors in the top tax bracket, though the math remains favorable for those in lower brackets as well. This is a level of taxable-equivalent yield that has rarely been seen over the past decade.
This chart from J.P. Morgan shows that investment-grade municipal bonds currently yield more than many fixed-income alternatives.
Source: J.P. Morgan
What makes the current municipal bond opportunity particularly interesting is that the sell-off has occurred despite relatively healthy state and local government finances.
Municipal credit quality improved substantially following the pandemic as federal assistance, economic growth, and stronger tax collections helped governments rebuild their financial reserves. Although reserve balances have declined from their pandemic-era peaks, they remain well above historical averages. J.P. Morgan highlights that state tax revenues increased 6.3% during the 12 months ending June 30, 2026, with growth distributed across states and major revenue categories. 1
These stronger collections provide an important financial cushion for municipal issuers and could grow further in the years ahead. State and local governments generally rely on a combination of income taxes, sales taxes, property taxes, and other revenue sources to fund essential services and repay outstanding debt. The so-called Blue Wave of the recent midterms, with several Democratic candidates winning key state elections, has the potential to increase taxes and shore up sagging municipal balances even further.
Meanwhile, average credit quality for the broader muni sector remains high relative to the number of issuers and bond types available, with much of the major muni bond index composed of very solid investment-grade issuers.
The Time For Munis Is Now
For investors, the sell-off in the municipal bond sector could represent a major buying opportunity. High tax-equivalent yields coupled with strong credit quality fundamentals make the sector compelling, and munis tend to deliver strong total returns when yields are this elevated.
J.P. Morgan’s research highlights that when the yield on a 30-year municipal bond exceeds 4.5%, the average subsequent 12-month return was approximately 7.0%, compared with 4.2% during other periods. The 30-year municipal yield remained above that threshold in late October/early November. While historical performance does not guarantee future results, the findings suggest that elevated starting yields can provide an attractive foundation for returns.
With this in mind, the time for municipal bonds is now.
ETFs could provide the best entry point into the sector. Passive funds offer broad exposure, but the recent market repricing may also create opportunities for active management. Unlike passive strategies, which generally track broad municipal bond indexes, active managers can evaluate individual issuers, adjust portfolio duration, and identify securities whose prices may not accurately reflect their underlying credit fundamentals—and active managers have historically outperformed their passive peers in this sector.
Active Municipal Bond ETFs
These ETFs were selected for their ability to provide low-cost, active exposure to the municipal bond market. Sorted by YTD total return, they range from -1.8% to 3.1%, carry expense ratios of 0.12% to 0.65%, and have assets under management of $418 million to $3.4 billion. Current yields range between 2.8% and 4%.
| Ticker | Name | AUM | YTD Total Ret (%) | Yield (%) | Exp Ratio | Security Type | Actively Managed? |
|---|---|---|---|---|---|---|---|
| SMMU | PIMCO Short Term Municipal Bond Active ETF | $890M | 3.1% | 2.9% | 0.35% | ETF | Yes |
| MEAR | iShares Short Maturity Municipal Bond Active ETF | $1.1B | 2.8% | 2.8% | 0.25% | ETF | Yes |
| IMNU | iShares Intermediate Muni Income Active ETF | $919M | 1.7% | 3.6% | 0.41% | ETF | Yes |
| HMOP | Hartford Municipal Opportunities ETF | $576M | 1.7% | 3.5% | 0.29% | ETF | Yes |
| CGMU | Capital Group Municipal Income ETF | $3.36B | 1.6% | 3.9% | 0.27% | ETF | Yes |
| MUNI | PIMCO Intermediate Municipal Bond Active ETF | $2B | 1.6% | 3.3% | 0.35% | ETF | Yes |
| AVMU | Avantis Core Municipal fixed-income ETF | $148M | -1.8% | 3.9% | 0.15% | ETF | Yes |
The recent municipal bond sell-off has created one of the most attractive fixed-income opportunities in years.
With tax-equivalent yields approaching 8%, valuations near multidecade lows, and state and local government finances remaining relatively healthy, investors can access substantial tax-exempt income without taking on excessive credit risk. Strong tax collections, elevated reserves, and the possibility of additional infrastructure support following the midterm elections provide further reasons for optimism.
Although interest-rate volatility and heavy issuance could continue pressuring prices, higher starting yields offer an attractive foundation for long-term returns, with potential capital appreciation if market conditions stabilize.
Bottom Line
The recent municipal bond sell-off has created a compelling opportunity for investors to capture historically attractive tax-exempt yields, benefit from strong credit fundamentals, and position their portfolios for potential capital appreciation through diversified municipal bond ETFs.
1 J.P. Morgan (October 2026). The great municipal repricing: why now may be the best opportunity in years


