


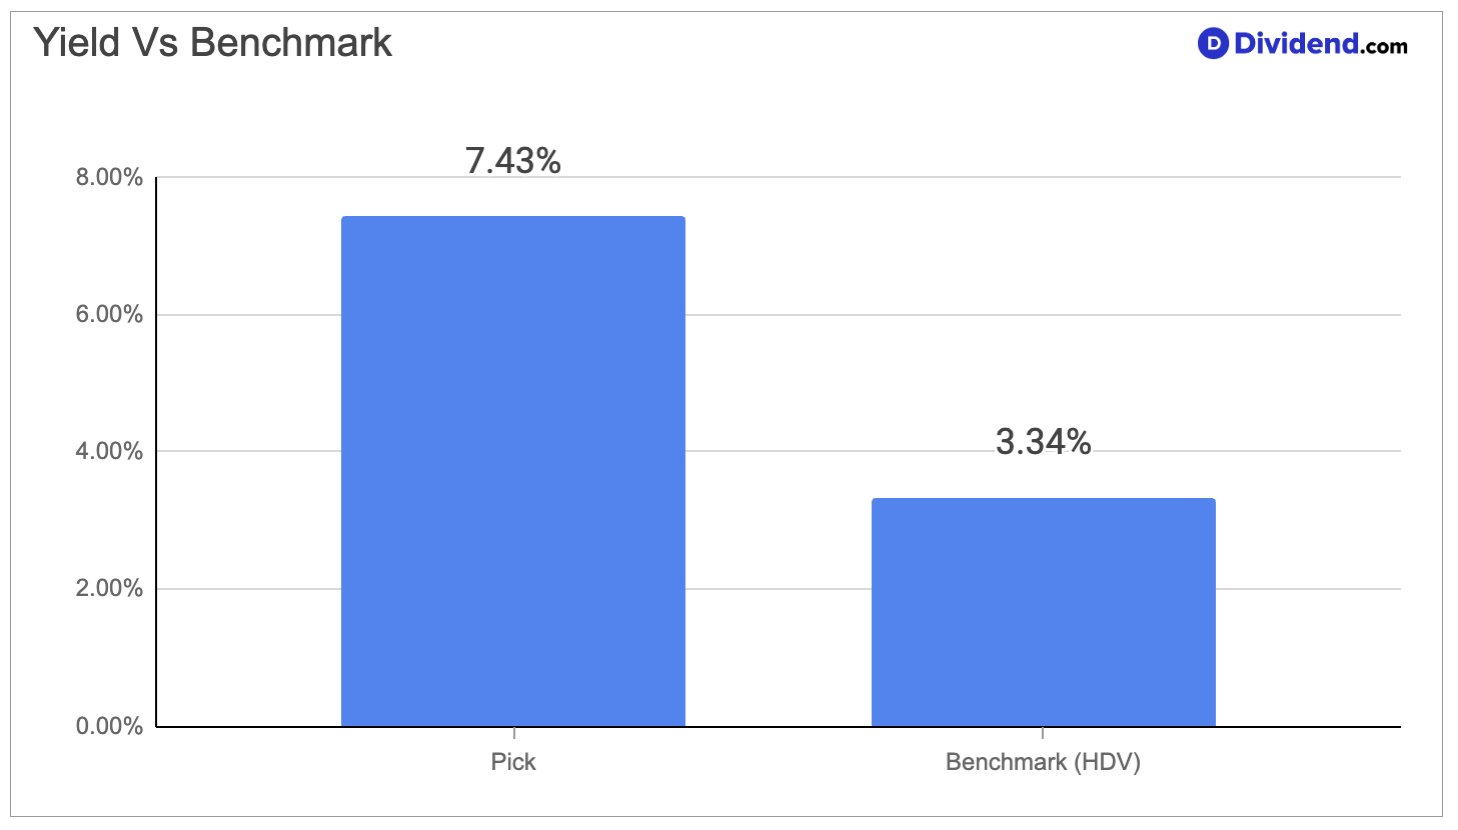
A 7.43% forward yield puts this real estate company in the top 20% of all dividend paying stocks, and that yield comes attached to a business model built for stability rather than speculation. The company owns the land and buildings behind some of the most heavily trafficked entertainment properties in the country, then leases them back to operators on long-term contracts. Those operators, not the landlord, handle taxes, insurance, and maintenance, which keeps the rent collection process simple and predictable.
The tenant base is concentrated among a small number of large, well-capitalized operators, which cuts risk from turnover but ties results closely to the fortunes of just a couple of major partners. Management has also been pushing the portfolio beyond its original footprint into wellness, sports, and leisure real estate, funding new development for operators who would rather not own their own buildings. That expansion strategy, combined with a payout ratio that runs a bit hot against sustainable growth, is exactly the kind of tension a High Yield investor needs to understand before buying in.
We increased our position in this name within the Best High Dividend Stocks Portfolio. The move reflects continued confidence in a durable rent collection model, a long track record of dividend increases, and a balance sheet that still has room to fund new deals without stretching too far. For a portfolio built around high, sustainable income, adding to a position that combines a top-tier yield with contractual cash flow protection fits the mandate directly.


