


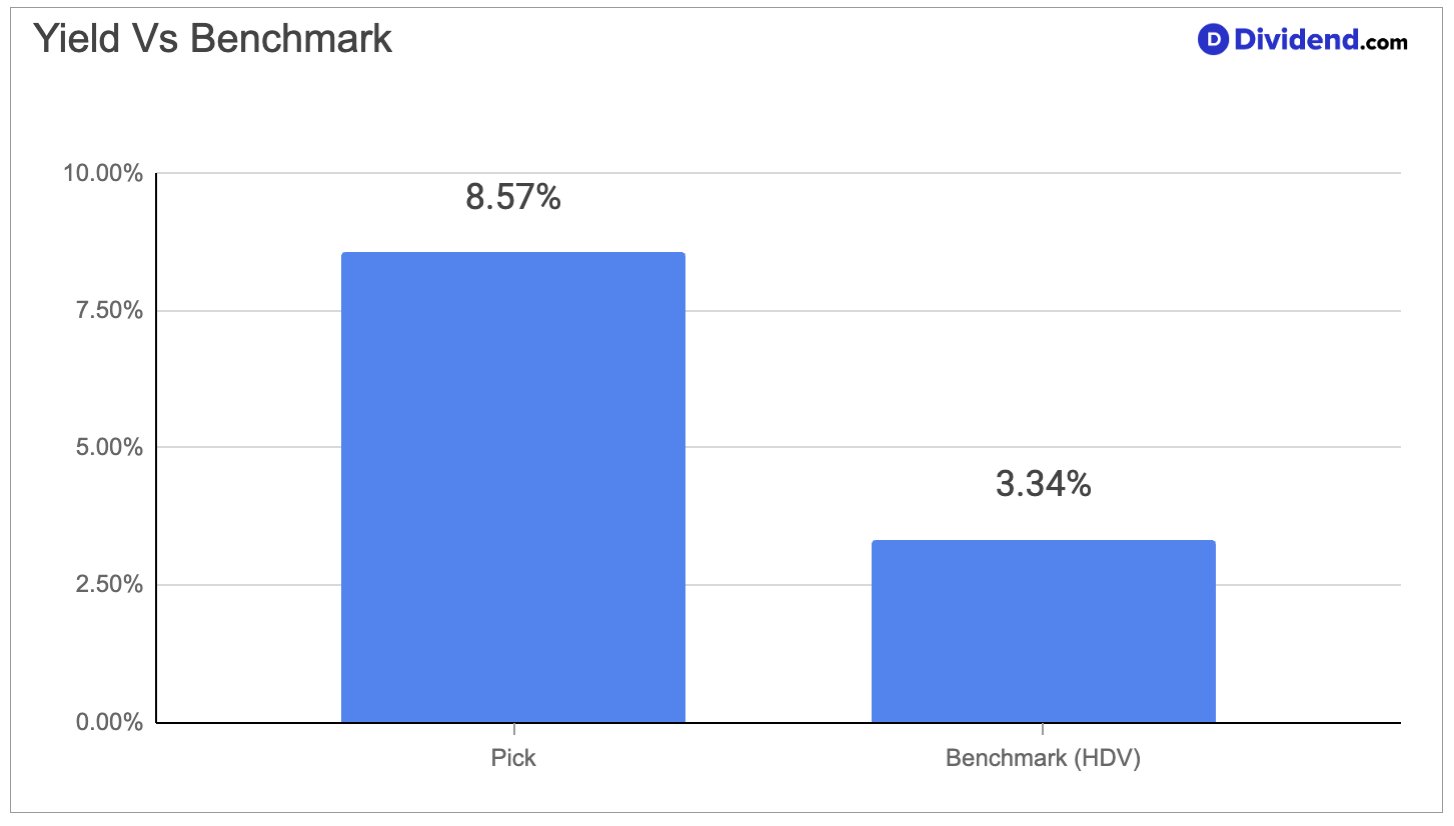
A real estate investment trust that owns casino properties now offers an 8.57% forward dividend yield, well above the 6.0% average for its specialty REIT peer group. The quarterly payout of $0.82 a share was raised 5% this summer, after cash flow per share grew 10% from a year earlier. A high starting yield paired with fresh dividend growth is the core reason we increased our position.
The trust buys casino real estate and leases it back to regional gaming operators under long-term triple-net leases. Tenants pay the taxes, insurance, and upkeep, so rent arrives regardless of how the gaming floor performs in any given month. Growth comes from acquisitions, funded construction projects, and rent increases written into existing leases. The development pipeline is unusually visible, with a major urban casino opening in early 2027 and two tribal gaming projects moving forward. The main risks are a concentrated tenant base, higher borrowing costs on future deals, and the spread of online gaming in several states. The shares now trade 23% below their 52-week high, which has pushed the yield higher even as the underlying rent stream kept growing.
We increased our position in the Best High Dividend Stocks Portfolio because the yield now ranks in the top 20% of all dividend stocks while leverage sits below management’s own target range. The pullback gives income investors a chance to buy contractual rent growth at a discounted price.


