


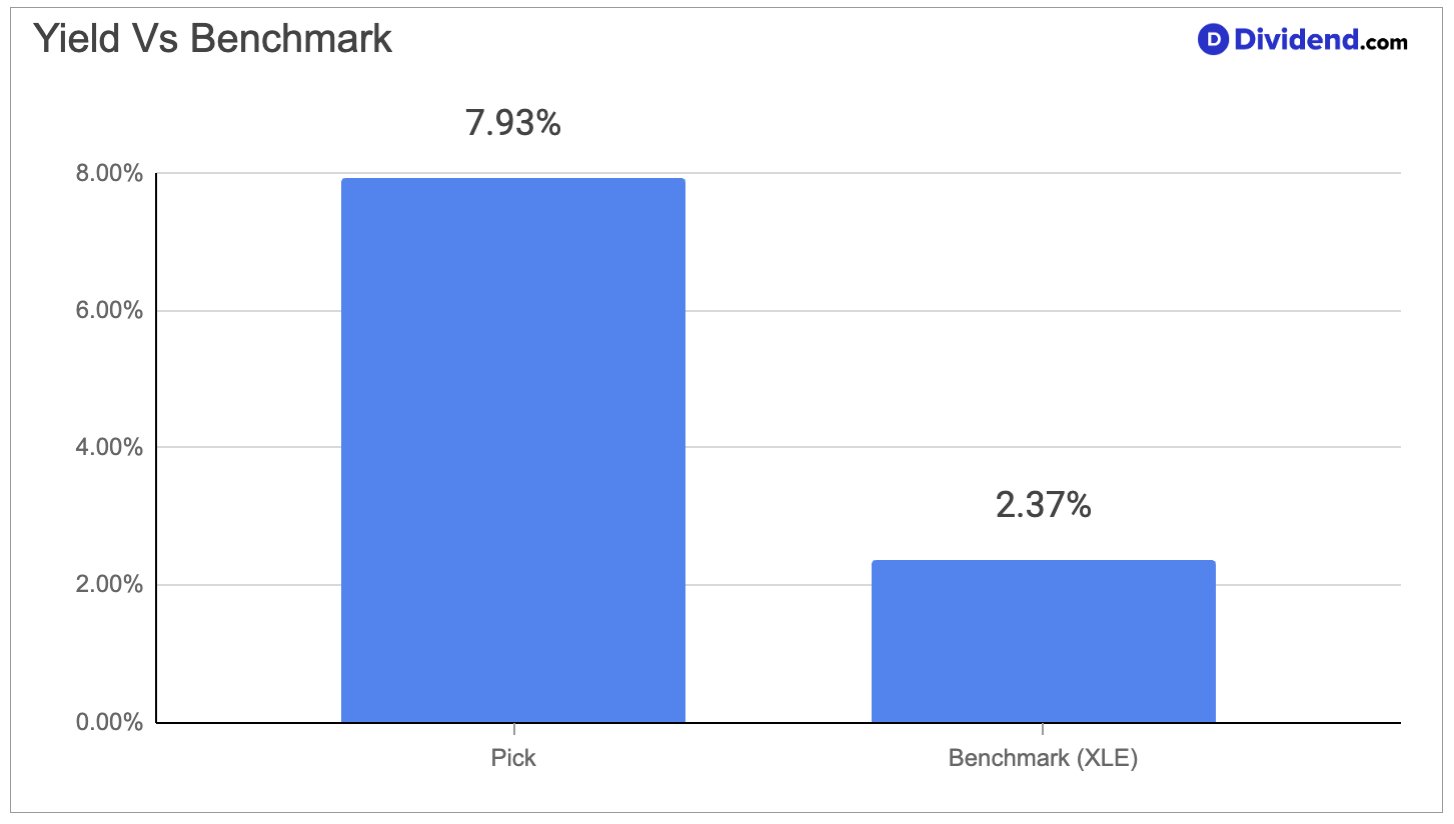
This energy infrastructure partnership moves natural gas, crude oil, and produced water for some of the largest operators in the country, and it does so with a beta of just 0.66, well below what most investors expect from an energy name. Its dividend has grown at a 20% compound annual rate over the past 3 years, a pace that ranks among the top 20% of all dividend paying stocks we track, and the stock now carries a forward yield of 7.93%.
The business itself doesn’t drill or explore. It builds and operates the pipelines, processing plants, and water systems that let other producers get their output to market, which gives it a fee-based revenue stream that’s less exposed to swings in commodity prices than the companies it serves. Recent growth has come from a mix of organic expansion and a sizable acquisition that added new drilling acreage and processing capacity, while the biggest risk on the horizon is a heavy reliance on a single customer relationship and one core production basin.
We’re adding this stock to the Best Energy Dividend Stocks Portfolio because it combines a well-covered, high-yield payout with a growth profile that doesn’t depend on volatile energy prices to keep working. Its low correlation to broader market swings also makes it a useful diversifier for investors already holding energy names with higher volatility. The combination of income, growth, and reduced price sensitivity is exactly the mix this portfolio looks to capture.


