


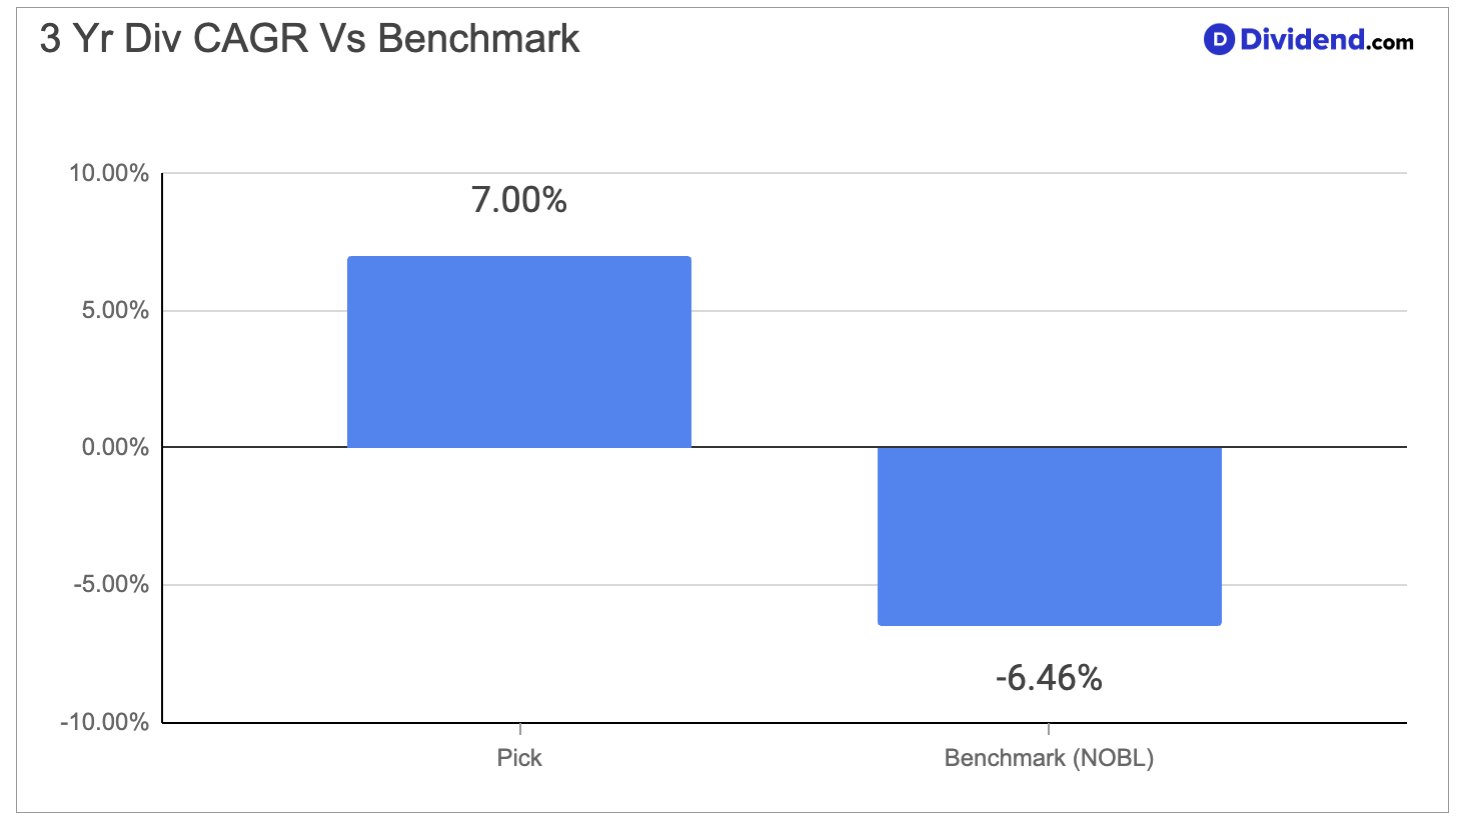
A regional bank with a forward dividend yield of 2.50% just joined our quality dividend lineup, and the numbers behind that addition are worth a closer look. Its beta of 0.71 points to a stock that moves less than the broader market, and its 3 year dividend growth rate of 7% outpaces most peers in its industry.
The bank operates across several states and runs both a retail banking arm and a back office services business that supports smaller institutions. Recent loan growth has come from multiple regions rather than one concentrated area, and expense discipline has kept credit losses low even as the company works through a large recent acquisition. That combination of geographic spread and integration risk is exactly the kind of tradeoff our scoring framework is built to sort through.
This addition reflects the Best Dividend Stocks Portfolio’s mandate to find companies that pair reliable income with a business that can keep growing into that income. A 15 year streak of consecutive dividend increases, a low payout ratio and a debt load well under the industry average all point to a company with room to keep raising its payout even as it digests a major merger.


