


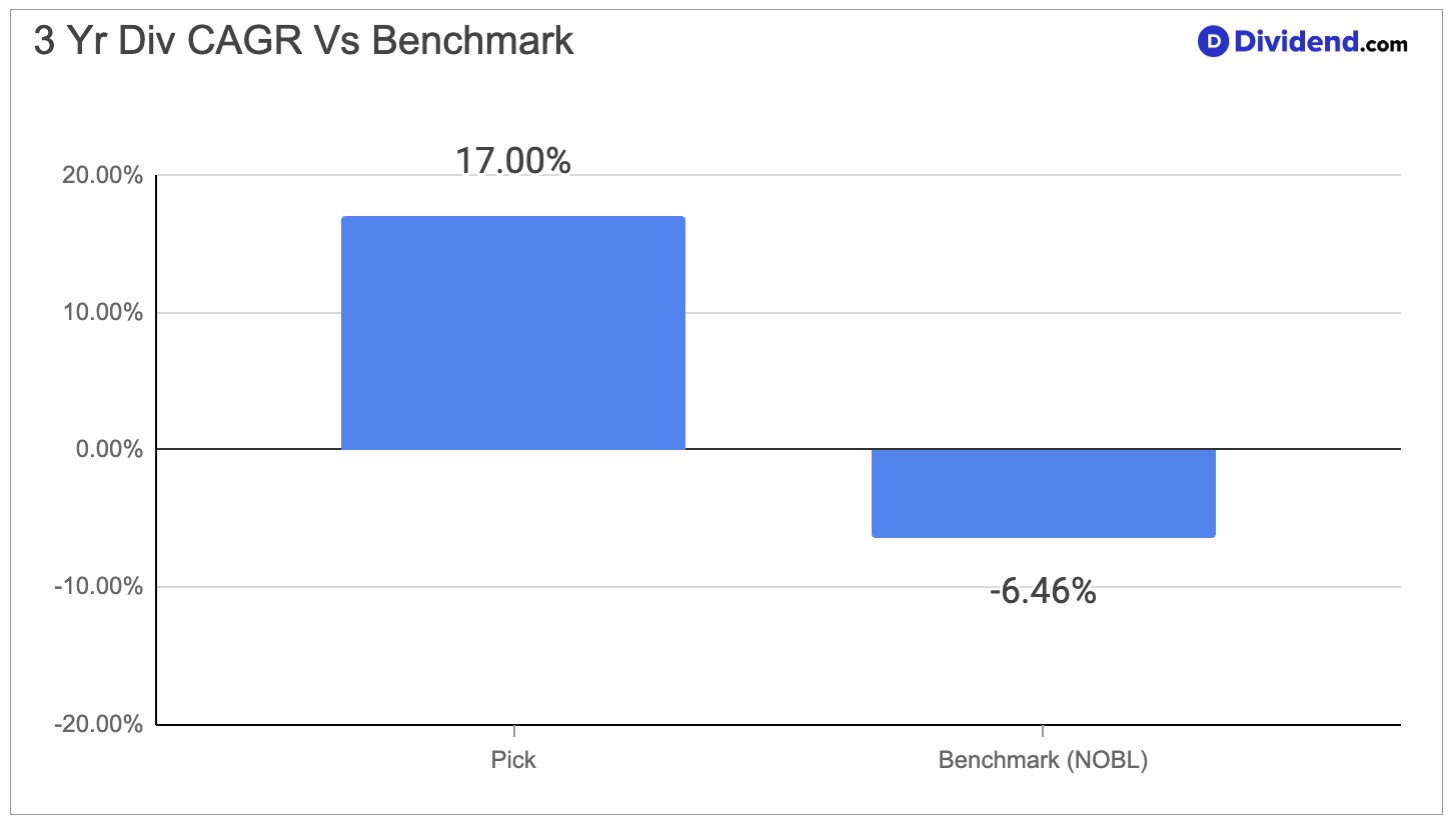
A bank holding company built around retail banking, wealth management, and treasury services in a market it knows well has landed on our radar for its dividend quality. Its stock carries a beta of 0.71, a level that suggests price swings tend to run lighter than the broader equity market, which helps smooth out a diversified income portfolio. Its dividend per share has grown at a 17% compound annual rate over the past three years, a pace that ranks in the top 20% of dividend-paying stocks in our coverage. That mix of a defensive risk profile and fast dividend growth is unusual among regional banks right now, and it’s a combination worth understanding in more depth.
The company operates in a market dominated by just three major banks, and that concentrated competitive landscape has worked in its favor for decades. Recent quarters point to broad strength across the business, with new loan production climbing sharply and net interest margin widening as the local economy benefits from ongoing reconstruction and infrastructure spending. Digital adoption among its customer base is rising too, a sign that technology investment is starting to pay off.
Some near-term expense pressure and a modest uptick in loan losses tied to seasonal patterns are worth watching, though management has attributed both to factors that don’t point to a deeper credit issue.
This stock has just been added to our Best Dividend Stocks Portfolio, reflecting its blend of dividend growth, balance sheet discipline, and below-average volatility. Its inclusion fits a portfolio built around steady income backed by financial strength rather than yield alone. Investors looking for exposure to a growing regional economy through a well-capitalized bank may find this addition worth a closer look.


