


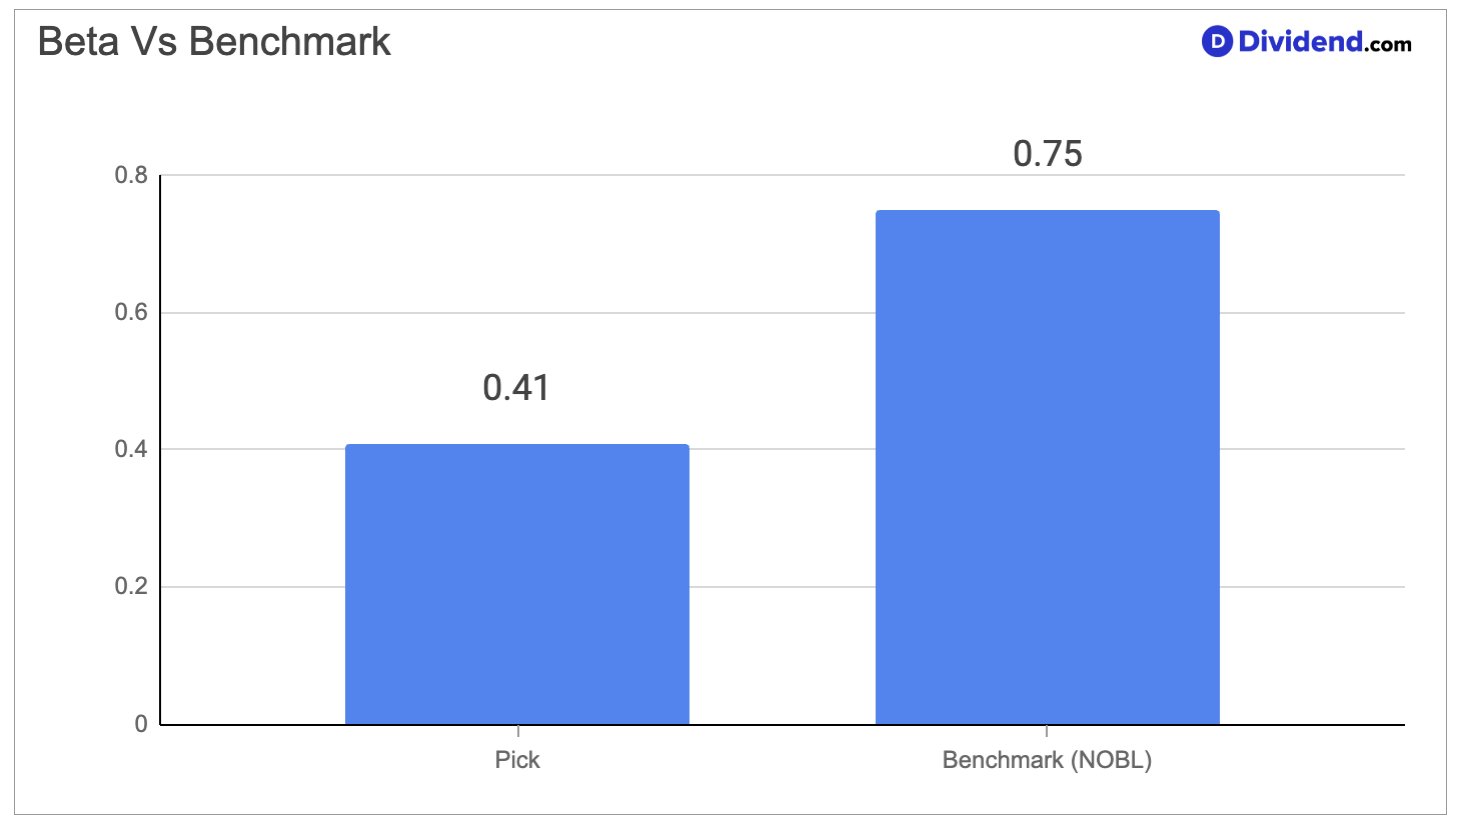
A global snack and confection maker with operations in more than 150 countries is drawing fresh attention from our Quality Dividend team. The company carries a beta of just 0.41, meaning its stock price moves with far less correlation to the broader market than most of its peers. Its dividend has also grown at a 7% compound annual rate over the past three years, a pace that outstrips much of the consumer staples group. That combination of low volatility and steady payout growth is exactly what quality-focused income investors look for.
The business itself sits in the packaged foods space, with a portfolio built around biscuits, baked snacks, and confectionery products sold across both developed and emerging markets. Management has leaned into emerging market demand as a primary growth engine, with double-digit gains in some regions during the most recent quarter.
That growth has not come without friction. A temporary drag on gross margin tied to inventory timing, along with ongoing input cost pressure in the confectionery category, has kept some caution in the stock’s near-term sentiment. Even so, the underlying cash flow generation and decades-long commitment to dividend growth continue to support its case as a core holding.
We have increased our position in this name within the Quality Dividend Stocks Portfolio. The move reflects confidence that the company’s diversified geographic footprint and disciplined balance sheet management can carry it through a period of margin normalization. For a portfolio built around consistency and downside protection, adding to a low-beta name with a long dividend increase history fits the mandate well.


