


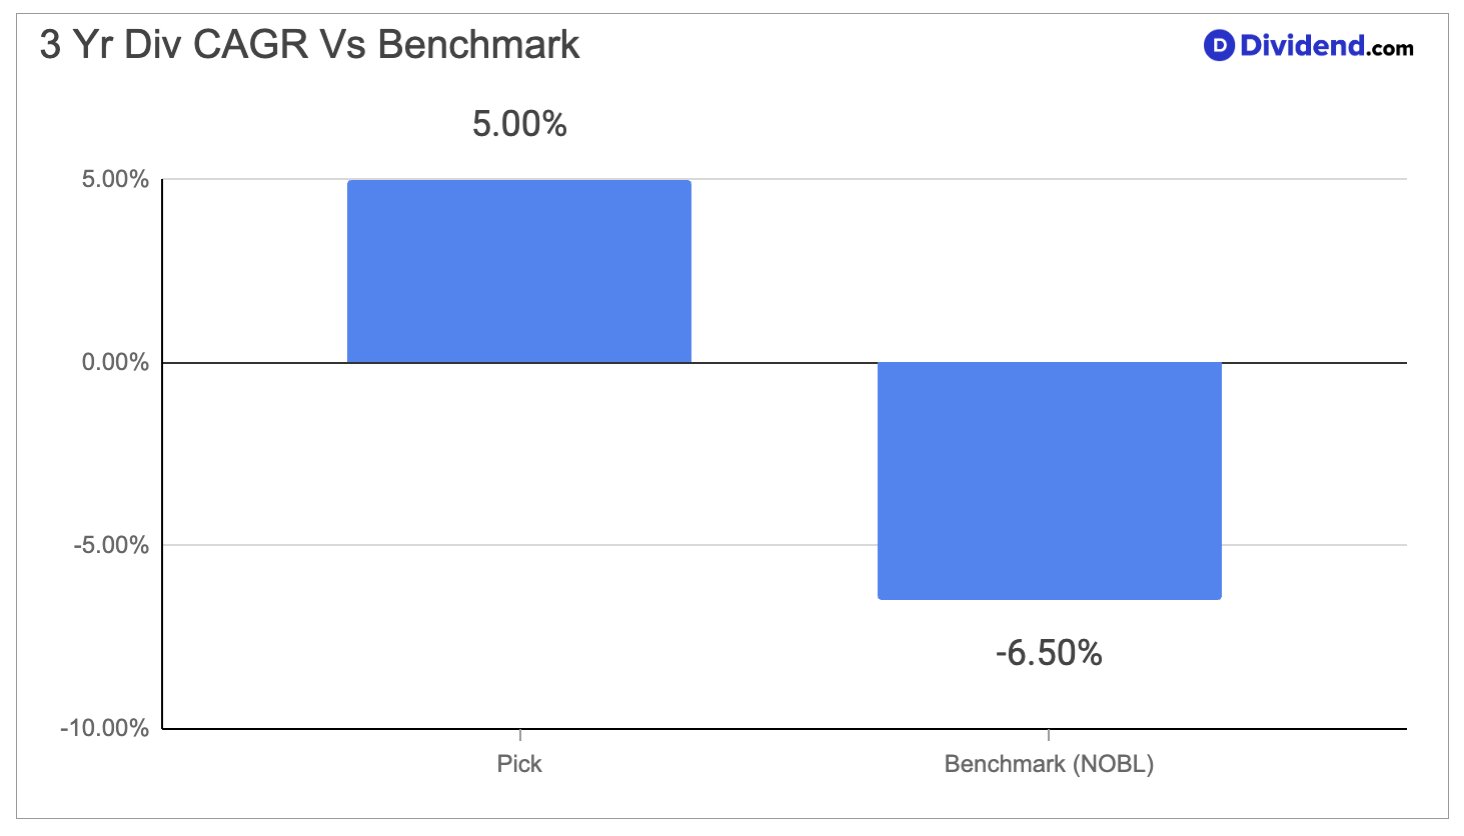
A well-established community bank serving New England has just seen its allocation increased within our Best Dividend Stocks Portfolio, and the underlying numbers explain the decision. The stock carries a beta of 0.79, meaning its monthly price swings run below what you’d expect from the broader equity market, a trait that matters to income investors who want steady exposure to financials without excess volatility. Its three-year dividend growth rate sits at 5%, a moderate but consistent pace that shows the payout has kept climbing even as rate cycles shifted underneath it.
The bank runs a relationship-driven model built around low-cost, sticky deposits and disciplined underwriting, and it recently expanded its regional footprint through an acquisition that pushed total assets past $25 billion. Deposit growth has come in strong without forcing the bank to pay up for funding, and its commercial loan pipeline has grown quickly, which points toward healthier lending activity in the back half of the year. At the same time, heavier payoff activity in commercial real estate and a more competitive deposit market are trimming some of that momentum, a reminder that even well-run regional banks face cyclical pressure on both sides of the balance sheet.
This increased position reflects our continued confidence in the bank’s ability to pair a dependable payout with prudent balance sheet management, a combination that fits squarely within the Best Dividend Stocks Portfolio’s mandate for quality and consistency.


