


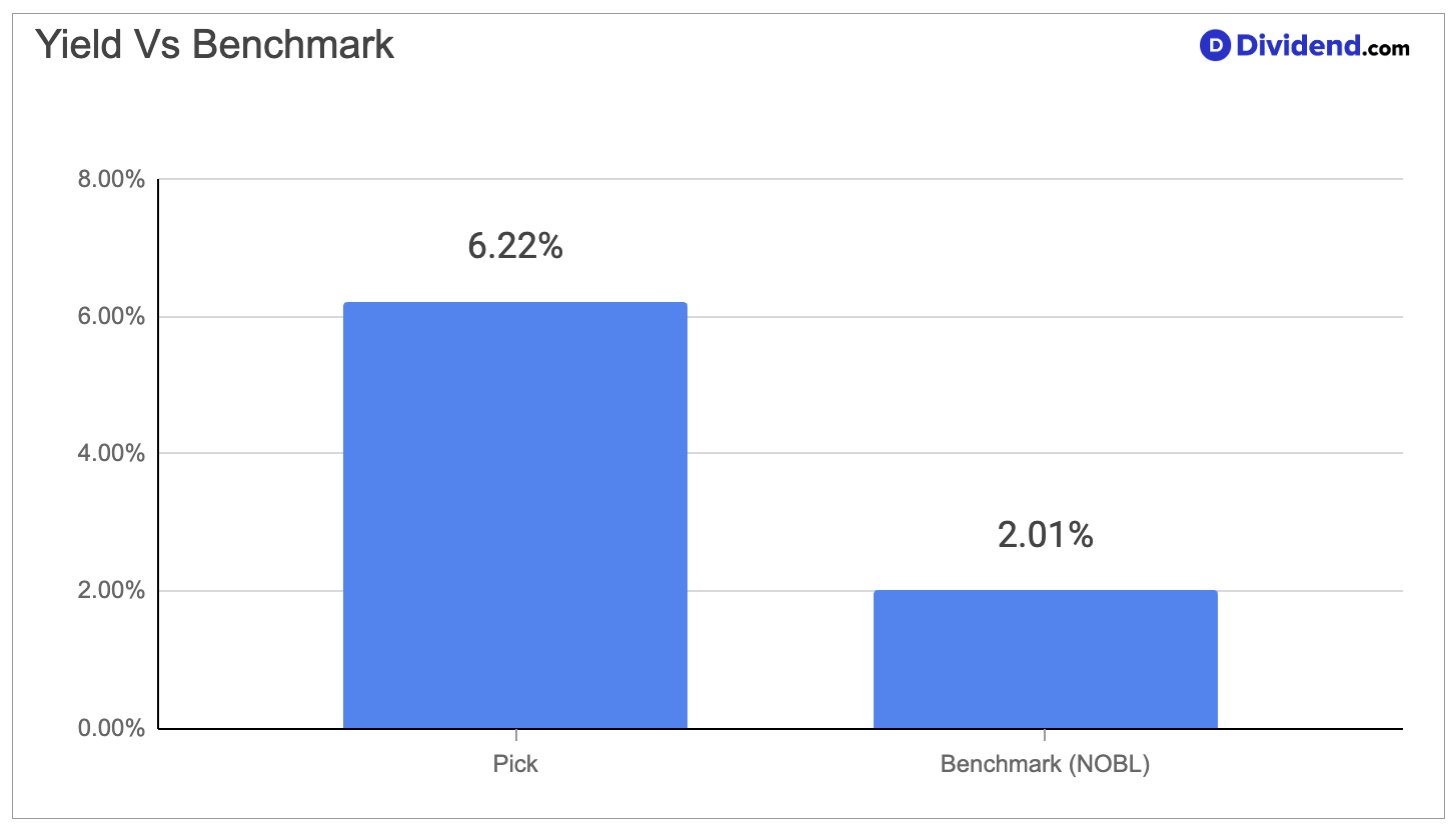
We increased our position in a mega-cap midstream energy partnership that pipes, processes, stores, and exports natural gas, crude oil, and natural gas liquids across North America. The units offer a 6.22% forward yield, a low 0.48 beta, and a steady 4% 3-year distribution growth rate, pairing strong income with calmer price swings than the broader market.
Most of the partnership’s cash flow comes from long-term, fee-based contracts, so results depend more on how much product moves through its network than on commodity prices. Record second-quarter earnings and a 33% jump in marine terminal volumes show that global demand for U.S. energy is feeding directly into results. A $6.5 billion slate of new processing plants, fractionation capacity, and export terminals is already under construction, and most of the capital behind 2027 growth is committed. The picture carries some risks. Export fees are softening as rivals add capacity, higher spending will trim near-term free cash flow, and a long-serving co-chief executive is retiring.
We increased our position in the Best Dividend Stocks Portfolio because this holding pairs a high, well-covered yield with 29 consecutive years of distribution raises. Its low market sensitivity and largely contracted growth pipeline fit the portfolio’s focus on durable, balanced income.


