


A regional bank with more than five decades of steady branch growth just earned a place in our Dividend Protection Stocks Portfolio, and its 0.51 beta is a big part of why. That low beta means the stock barely moves with the broader market, which is exactly the kind of behavior conservative income investors want from a core holding.
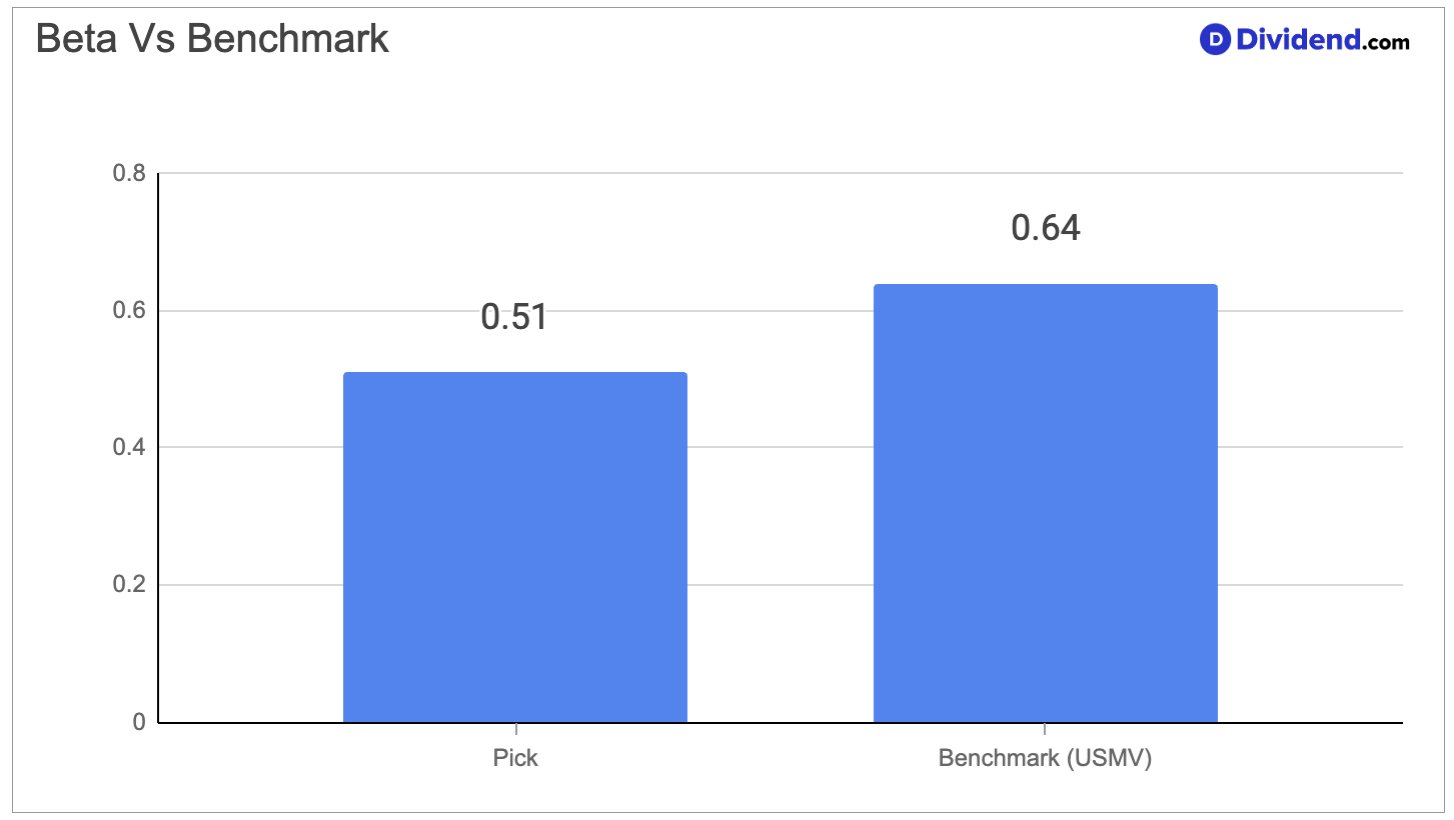
The company runs its branch network inside a single, fast growing region rather than spreading thin across the country, and that focus shows up in the numbers. New customer growth has been accelerating, loan demand from local businesses has been climbing, and management has been raising its own guidance rather than walking it back. The one blemish worth watching is a single troubled commercial real estate loan, though the bank expects to resolve it through a sale without much of a loss. Competition in its home market has picked up as newer players chase growth with looser lending terms, but the company has said it will compete on price rather than loosen its own underwriting standards, a decision that protects the balance sheet over the long run.
We added this stock to the Dividend Protection Stocks Portfolio because it checks nearly every box our safe dividend framework looks for, a long increase streak, a conservative payout ratio, low leverage, and a beta that keeps portfolio volatility in check. This is the kind of holding built to sit quietly in a retirement account and keep paying, year after year, without demanding much attention.


