


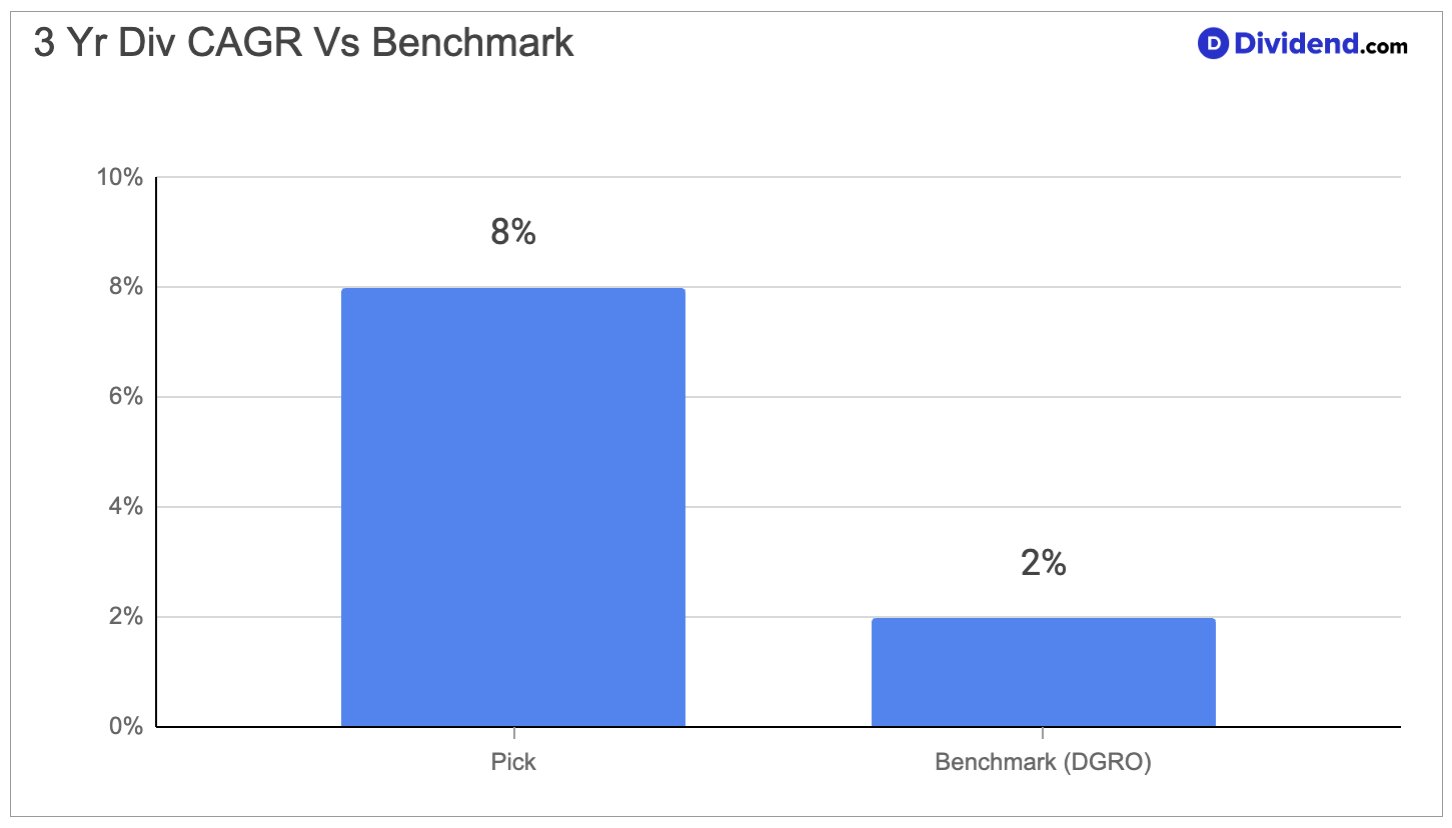
A global snack maker that sells cookies, crackers, chocolate, gum and candy in roughly 150 countries has grown its dividend at an 8% compound annual rate over the past 3 years. That pace is well ahead of the 3% average for its consumer products peers. The company has also raised its payout for 15 straight years, and analysts expect earnings per share to grow about 10% next year.
The business rests on century-old brands, large factories and deep distribution in emerging markets, where it keeps adding small neighborhood stores. Its latest quarter showed growth driven by higher sales volumes, along with wider profit margins as cocoa costs eased from record highs. It grew volumes without cutting prices, which is uncommon among packaged-food makers today. The risks are real. Lower-income shoppers in the US are pulling back, consumer confidence in China remains weak, and management expects a cocoa shortfall next season. Debt also runs a bit higher than peers. Even so, the stock’s price has moved largely independently of the broader market, a useful trait for investors who want steady income.
We have increased our position in this stock within the Dividend Growth Stocks Portfolio. A long record of raises, recovering margins and a widening store network in fast-growing markets give the dividend a credible path to keep compounding. The full analysis explains how each piece fits the portfolio’s growth-first approach.


