


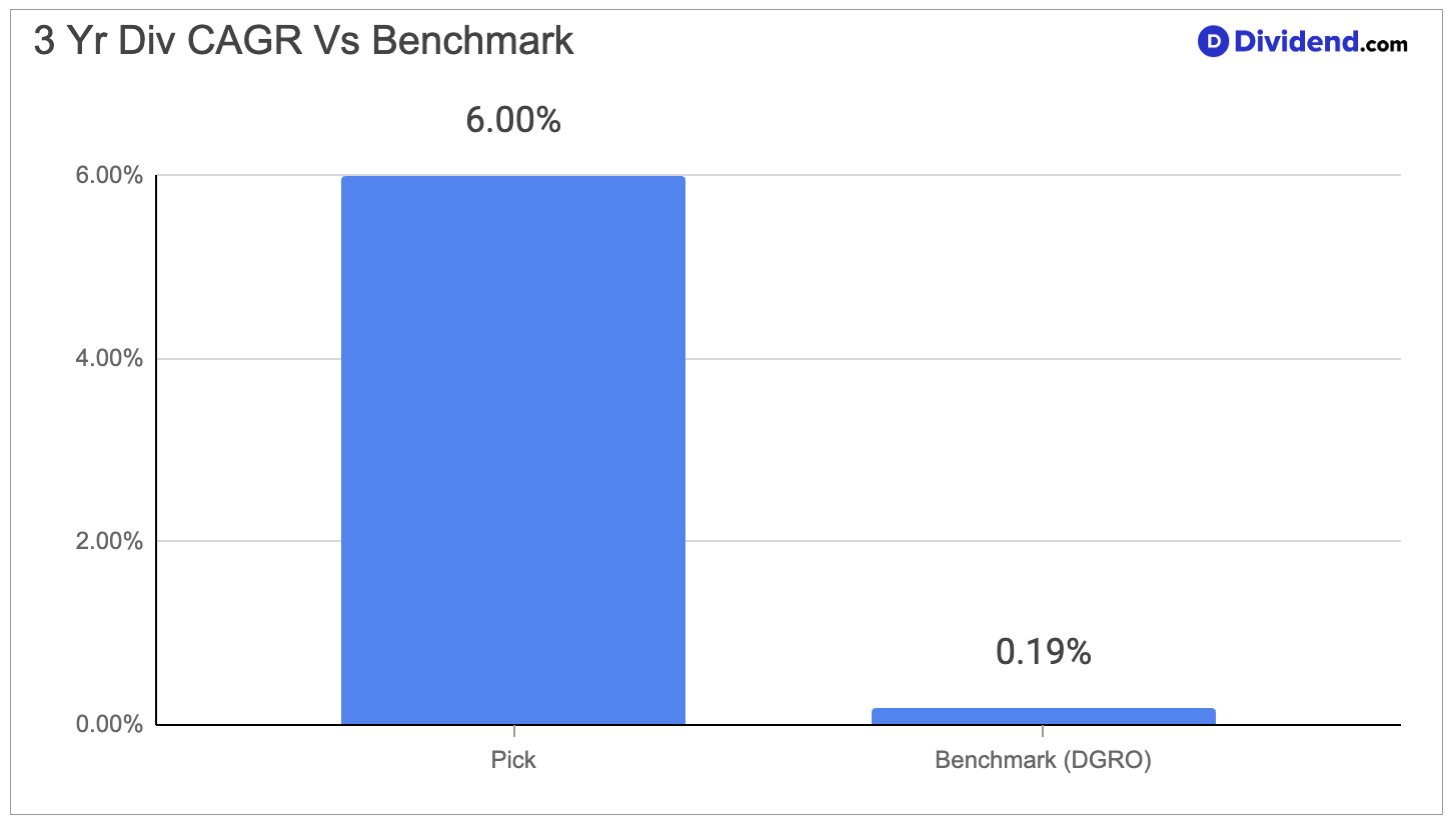
A diversified aerospace and defense manufacturer has grown its dividend at a 6% compound annual rate over the past three years, a pace that lands it in the top 40% of all dividend paying stocks we track. The business spans premium business jets, naval shipbuilding, armored vehicles, and government technology services, giving it exposure to both long defense contracting cycles and shorter commercial aviation demand. Record order backlogs and rising production across its shipyards and aircraft lines have pushed revenue and earnings higher this year, while management keeps investing in added manufacturing capacity to keep pace with demand. Supply bottlenecks for specialized components and a coming product transition in its jet lineup are worth watching, though neither looks likely to threaten the cash flow behind the payout.
A long dividend increase streak, a conservative payout ratio, and a debt load that stays in line with cash generation make this a name built for investors who want growth without taking on excessive risk. Steady demand from allied militaries and a business jet market that’s clearly recovering add further support to the outlook.
We increased our position in this stock within the Dividend Growth Stocks Portfolio, reflecting confidence that its backlog strength, balance sheet discipline, and multi-decade dividend consistency continue to fit our mandate of compounding income over time.


