


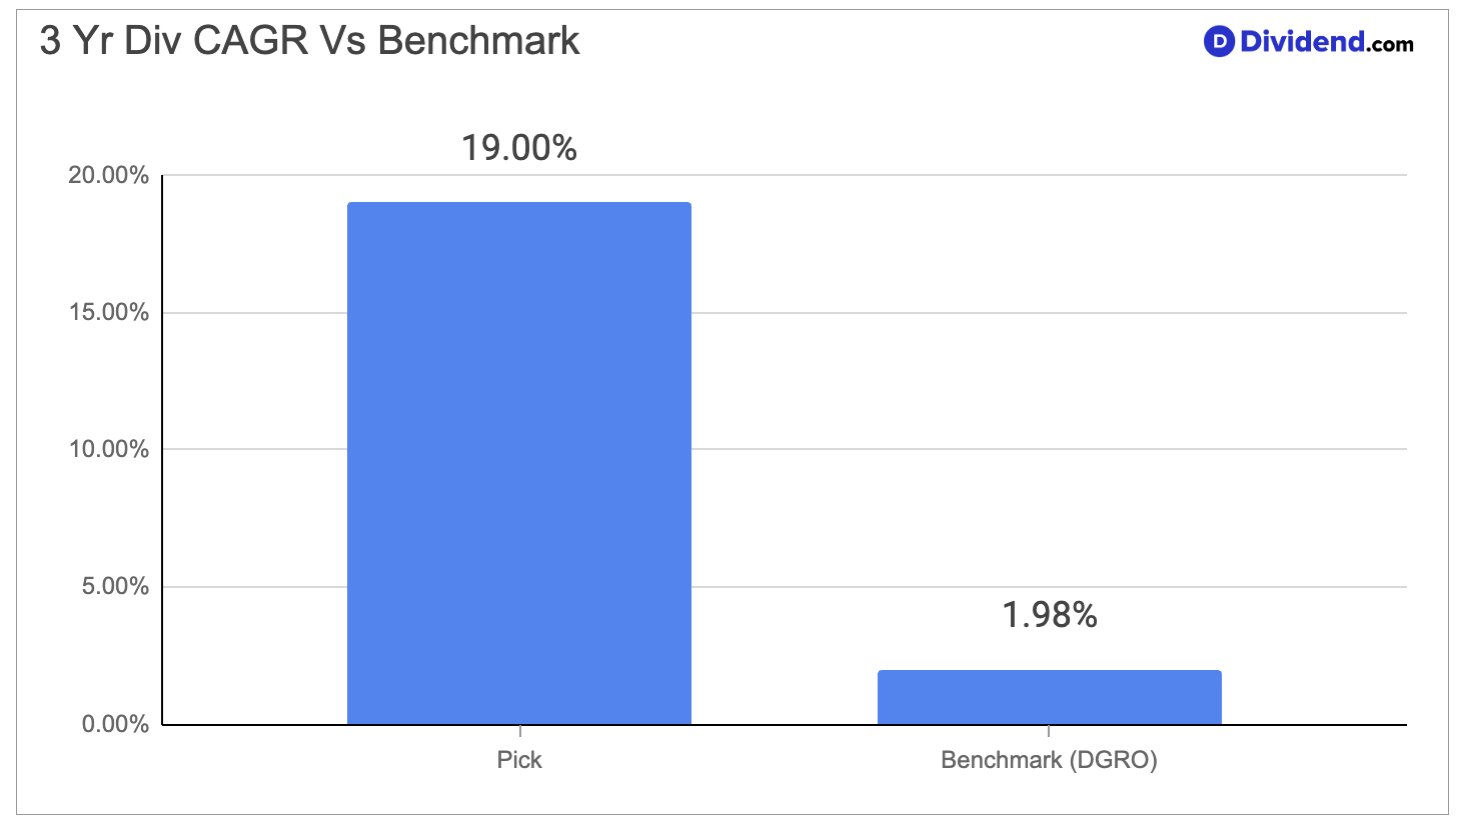
A commercial bank that serves as a financial bridge between the U.S. and Asia has grown its dividend at a 19% 3-year compound annual growth rate. That pace is more than 3 times the 6% banking average and ranks in the top 20% of all dividend stocks. The bank earns most of its income from business loans, commercial property loans and home mortgages. It funds that lending with a fast-growing base of low-cost checking deposits.
The bank’s capital cushion sits well above most regional peers, and operating costs take up less than 37 cents of every revenue dollar. Record loan and deposit balances in the latest quarter led management to raise its full-year growth targets. Wealth management and fee-based services are also emerging as a second source of growth. The risks are real but measured. Deposit competition could lift funding costs as a large batch of certificates of deposit comes due. A handful of commercial property loans have also stopped performing, and a rate cut would trim interest income modestly.
We have increased our position in the Dividend Growth Stocks Portfolio because this bank pairs rapid dividend growth with a payout that uses just 29% of forward earnings. It also holds more cash than debt, which leaves ample room for future raises. The full analysis explains why the case grew strong enough to add to our stake.


