


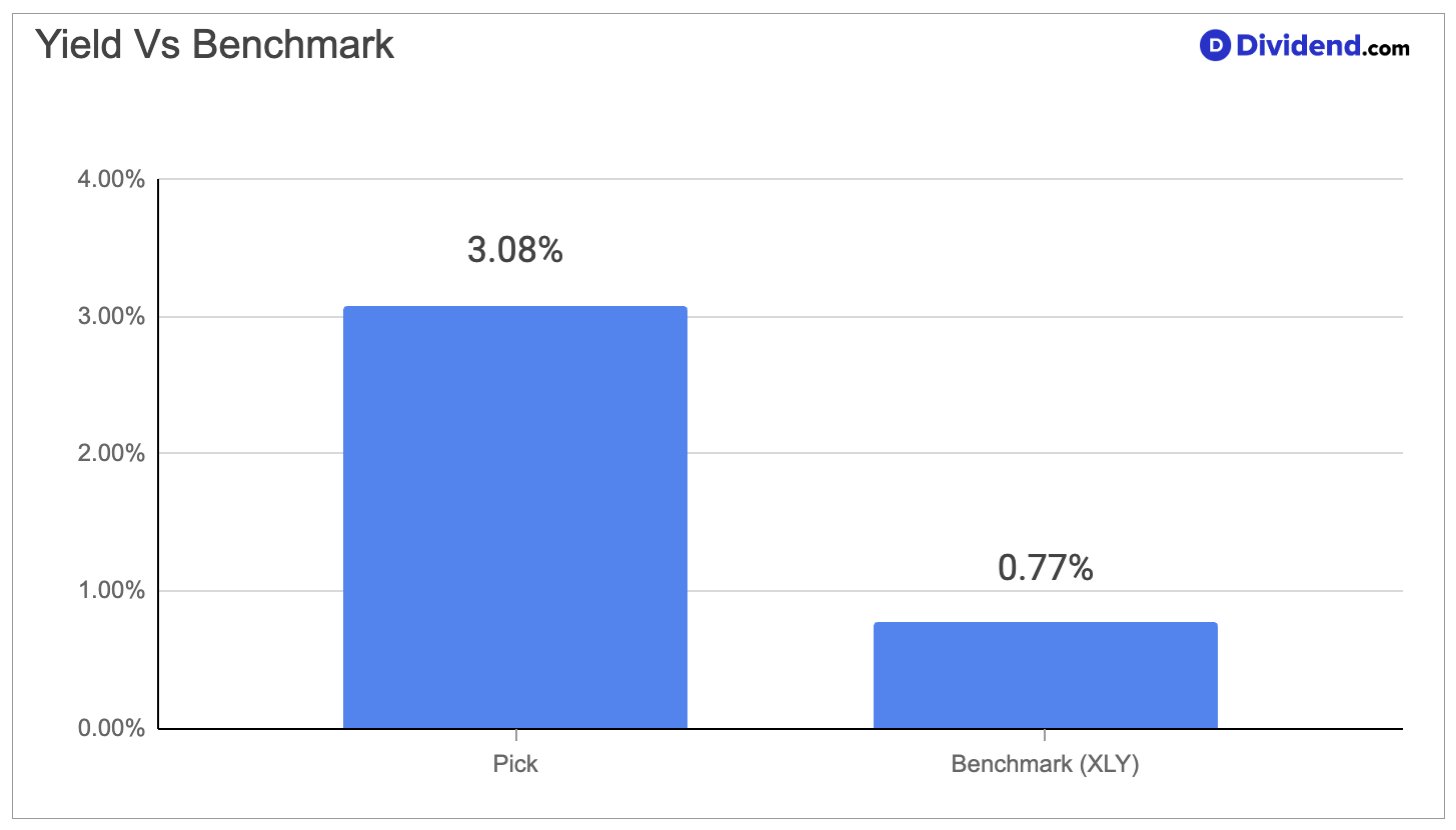
The world’s largest quick-service restaurant chain gives income investors steady cash flow with very little market sensitivity. Its 0.41 beta is less than half the peer average of 0.91, so the shares tend to move independently of the broader market. The dividend has grown at a 6% annual rate over the past 3 years, backed by 51 straight years of increases. The 3.08% forward yield also tops the industry average of 2.6%. Most of the company’s income comes from royalties and rent paid by franchisees, which keeps margins high and cash flow predictable.
The business is growing through a new beverage lineup that lifts average checks by about 50%, a loyalty program with close to 220 million active users, and steady gains in international markets. The main risks are weak industry traffic, ongoing softness in China, and a poorly executed value menu rollout in the U.S. That U.S. stumble has pushed the stock 27% below its 52-week high.
We have increased our position in the Best Consumer Discretionary Dividend Stocks Portfolio to take advantage of this pullback. The lower price lifts the yield and trims the valuation, while the long dividend record and the fee-based business model remain intact.


